Executive summary
Financial institutions are no longer experimenting with chatbots. They are putting AI agents into workflows that move money, change credit exposure, and touch a customer’s legal record. That is a different class of system — and regulators already treat it that way.
The institutions that will ship agents in 2026 are not the ones with the flashiest demo. They are the ones that can show, for every material action, what data was used, which policy applied, who was allowed to override it, and how the outcome can be reconstructed six months later in an exam.
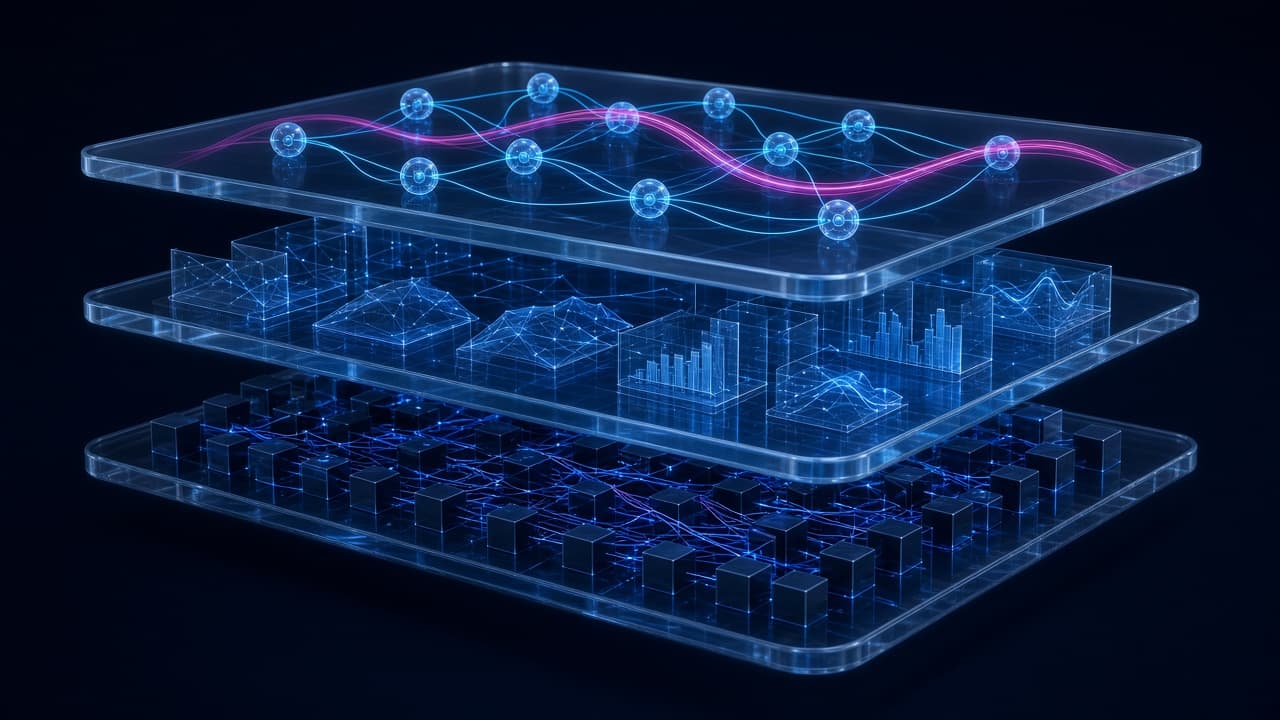
This paper lays out an operating model we use inside eForte’s Finance Studio: start with an audit-ready Foundational Data Layer, layer Applied AI that can be explained, then give Agentic Orchestration a narrow mandate with human supervision at the points that actually create risk.
Why 2026 is the year agents leave the sandbox
Three clocks are running at once. Real-time payment rails and ISO 20022-rich messages have made exception handling a seconds problem, not a batch problem. Credit teams are underwriting thin-file borrowers with cash-flow and alternative data that legacy scorecards were never designed to defend. And the EU AI Act, NIST AI RMF, and model-risk programs inside US banks now expect a human-readable trail for high-risk automated decisions — not a slide deck after the fact.
Meanwhile, most “agent” pilots still sit on top of fragmented cores, ticket queues, and spreadsheet overlays. The agent looks intelligent in a sandbox because a human has already cleaned the context. In production, that context is incomplete, delayed, or legally sensitive. The failure is rarely the model. It is the missing paper trail.